Paraguay president resigns after major bank collapse leaves 3 million customers unable to access money
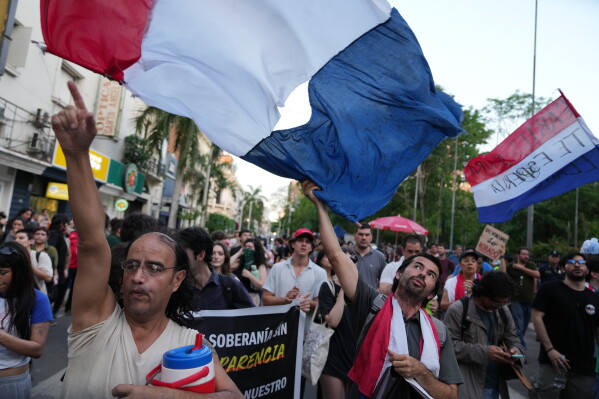
Millions of customers in Paraguay are waiting to regain access to their money following the collapse of Ueno Bank, one of the country’s largest digital lenders.
The crisis began on November 3, 2026, when the Central Bank of Paraguay placed the lender under resolution after discovering serious financial weaknesses that left it unable to meet the required solvency levels.
Ueno Bank reportedly had approximately 2.9 million customers, representing more than 60 per cent of the country’s adult population. Its sudden shutdown disrupted access to savings, payments, transfers and other banking services.
However, authorities have moved to reassure customers that the intervention does not automatically mean their deposits have been lost.
According to the Associated Press, the Central Bank plans to transfer customers’ deposits and recoverable assets to other financial institutions before liquidating the remaining assets of the troubled lender.
Officials have also begun opening accounts at other banks for affected customers. By Thursday, November 5, approximately 280,000 customers who banked exclusively with Ueno had reportedly been provided with new accounts as part of the transfer process.
Another important protection is Paraguay’s deposit guarantee scheme, which covers eligible deposits up to approximately 228 million guaraníes, equivalent to about US$38,000 per depositor.
The guarantee is expected to protect around 97 per cent of Ueno’s depositors. However, customers with balances above the insured limit could face uncertainty over how much of their money they will eventually recover.
The crisis has also raised questions about the bank’s handling of public funds. Ueno reportedly held between US$800 million and US$850 million in public deposits, including money linked to state pension and health funds.
Meanwhile, investigations into the lender’s management have intensified. Prosecutors have charged 27 bank officials and business associates, while six executives have reportedly been placed in pretrial detention.
The bank’s collapse has also triggered a political crisis that culminated in President Santiago Peña’s resignation on November 5. Vice President Pedro Alliana has since assumed the presidency.
For millions of ordinary customers, however, the immediate concern remains the same: when will they be able to access their savings and resume normal financial transactions?
Although the government has outlined measures to protect depositors, the transfer and recovery process remains a major test for Paraguay’s financial authorities.